The UK’s accountancy regulator has delivered a decisive blow to five former executives of the collapsed government contractor Carillion, banning them following findings of reckless behavior in financial reporting. Among those sanctioned is Richard Adam, Carillion’s ex-finance director, whose 15-year ban effectively ends his professional career.
What Led to the Bans?
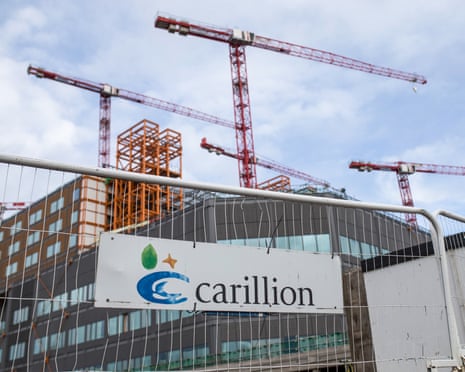
Carillion, once a multinational giant in construction and facilities management, employed approximately 43,000 people globally before its dramatic collapse in January 2018. Its liquidation marked one of the most significant corporate failures in UK history, sparking widespread disruption across public-sector projects including schools, roads, prisons, and hospital constructions.

The Financial Reporting Council (FRC) announced on Tuesday that it had imposed severe penalties on five former senior Carillion accountants. These sanctions follow earlier fines levied by the Financial Conduct Authority (FCA) against two key figures: Richard Adam and Zafar Khan, his successor as finance director and former financial controller. Adam was fined £232,830, while Khan received a £138,960 penalty for misleading investors.

The FRC has now banned Adam for 15 years, accompanied by a financial sanction of £222,019—reduced from an initial £550,000 to account for FCA penalties and settlement discounts. Khan faces a 10-year ban and a £60,228 fine, reduced from £225,000. Both men were also severely reprimanded.

Details of the Misconduct
The FRC’s investigation revealed that Adam and Khan engaged in misconduct spanning several critical areas of Carillion’s business between 2013 and the first half of 2017. This misconduct involved misrepresentations related to major UK construction contracts, complex transactions, and a supply chain finance facility, all of which distorted the company’s reported financial performance during that period.

In addition to Adam and Khan, the regulator identified three other senior accountants who “acted recklessly and failed to act with integrity” while preparing Carillion’s financial statements. These individuals, unnamed by the FRC, received bans ranging from two to eight years. The longest banned accountant faced an eight-year exclusion and a £45,000 fine, while the other two were banned for five and two years respectively, each fined £26,000. All three were severely reprimanded, with their fines reduced through settlement agreements.

Penrose Foss, the FRC’s executive director of investigations and enforcement, underscored the gravity of these failures: “The substantial sanctions imposed on these five individuals reflect the gravity of their failure to discharge their respective obligations to act with integrity in preparing financial information in the context of a large, listed company.”
The Fallout from Carillion’s Collapse
Carillion’s downfall was catastrophic. The company entered liquidation burdened by £7 billion in debt, triggering approximately 3,000 job losses and halting work on 450 projects. These included high-profile public-sector contracts such as the expansion of Liverpool Football Club’s stadium and the construction of two hospitals, both of which suffered significant delays and cost overruns running into hundreds of millions of pounds.
Financial troubles became public in 2017 when Carillion issued multiple profit warnings. In July, the company announced an expected £845 million provision against its construction contracts. This was followed in September by a further £200 million provision and a staggering £1.15 billion half-year loss. By November, the company warned it would breach banking covenants the next month, signaling imminent collapse.
The reckless financial reporting by senior executives not only misled investors but also masked the company’s deteriorating financial health, delaying necessary intervention and exacerbating the fallout.
Why This Matters
This case highlights the critical importance of integrity and accountability in corporate financial management, especially within firms that handle large public contracts and taxpayer money. The FRC’s stringent sanctions send a clear message: senior financial officers must uphold the highest standards of transparency and honesty to maintain trust in the markets and safeguard public interests.
For the broader business community, the Carillion debacle serves as a cautionary tale about the dangers of aggressive accounting practices and the need for robust regulatory oversight. Public-sector stakeholders and investors alike depend on accurate financial disclosures to make informed decisions, and failures in this area can have far-reaching economic and social consequences.
Looking Ahead
While these sanctions mark a significant step towards accountability, the full implications of Carillion’s collapse continue to unfold. The disruption to vital infrastructure projects and the impact on thousands of employees underscore the necessity for ongoing reform in corporate governance and financial oversight.
As regulators tighten scrutiny on financial conduct, companies across industries must prioritize ethical reporting and risk management. The lessons from Carillion’s failure will likely shape regulatory policies and corporate practices for years to come, aiming to prevent similar large-scale collapses in the future.