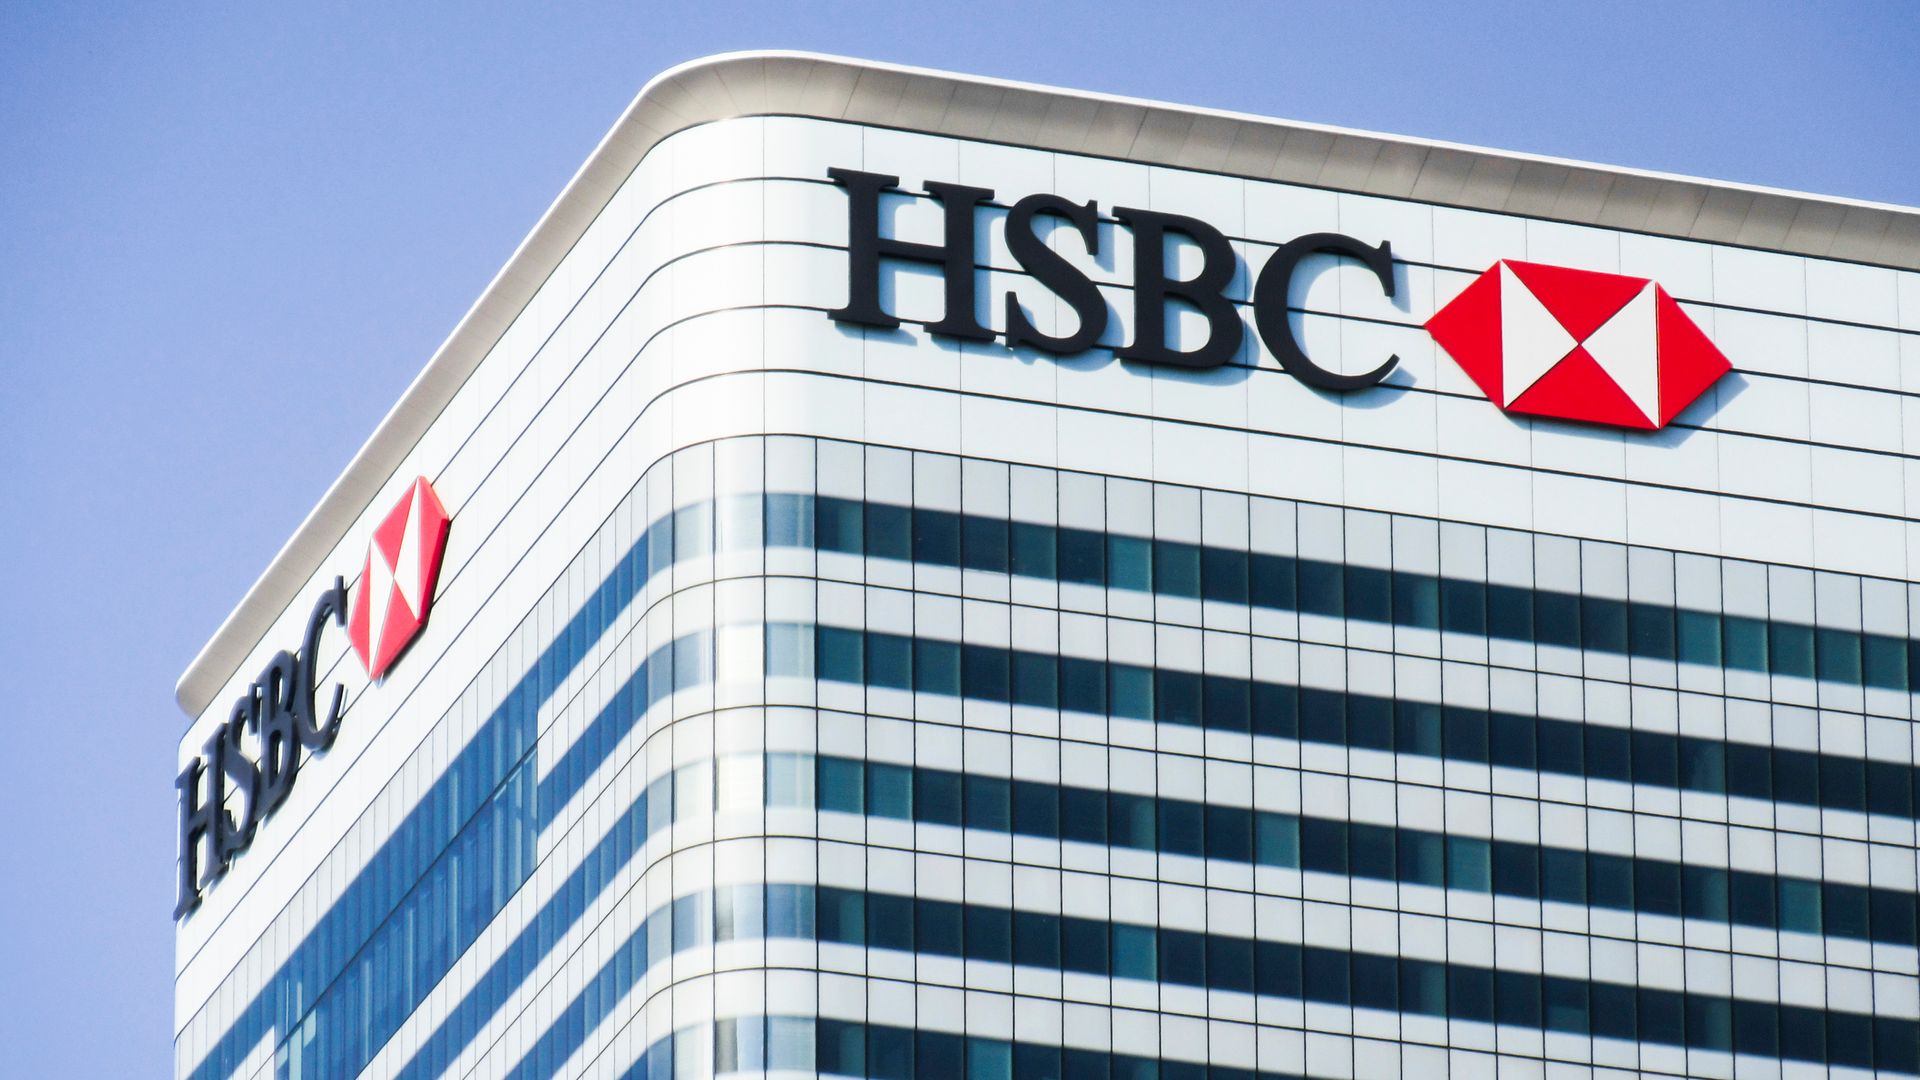
The United Kingdom’s banking sector continues to demonstrate robust profitability as another leading lender reveals staggering multi-billion pound earnings, significantly fueled by the recent surge in interest rates. This financial upswing arrives at a critical moment when the government is preparing to introduce a higher bank tax in its upcoming budget, signaling substantial shifts in the fiscal landscape for financial institutions.
Surge in Profits Driven by Rising Interest Rates
One of the UK’s largest banks has announced profits reaching into the billions, a growth largely attributed to the Bank of England’s aggressive interest rate hikes over the past year. As borrowing costs increased, the bank capitalized on wider interest margins, boosting revenues from loans and other credit products. This environment has created a lucrative opportunity for lenders, enabling them to expand their earnings despite broader economic challenges.
The recent interest rate adjustments were implemented by the Bank of England to combat inflationary pressures affecting the UK economy. While these measures aim to stabilize prices, they have simultaneously enhanced the profitability of banks by increasing the returns on their lending portfolios. The bank’s latest financial results underscore the significant impact of this macroeconomic shift, reflecting how policy decisions ripple through the financial sector.
Impending Higher Bank Tax and Government’s Fiscal Strategy
Amid this surge in profitability, the UK government is poised to introduce a higher tax on banks in its forthcoming budget—a move designed to tap into the sector’s windfall gains. The anticipated increase in the bank tax aims to generate additional revenue to support public finances, potentially funding services and investments during a period of economic uncertainty.
This policy shift aligns with broader government efforts to ensure that financial institutions contribute their fair share in light of extraordinary profits driven by external economic factors. While banks benefit from elevated interest rates, the government seeks to balance this by adjusting tax rates, reflecting a strategic approach to fiscal responsibility and equity.
The introduction of a higher bank tax could reshape profitability calculations for lenders, influencing their future strategies regarding lending practices, capital allocation, and investment. Stakeholders across the financial industry are closely monitoring these developments, aware of the potential implications for growth and shareholder returns.
Broader Implications for the UK Banking Sector and Economy
The current scenario presents a complex interplay between soaring bank profits and evolving regulatory landscapes. As lenders enjoy increased earnings from higher interest margins, they also face heightened scrutiny and taxation pressures. This dynamic raises important questions about the sustainability of profit growth and the role of banks in supporting economic stability.
For consumers and businesses, the impact of rising interest rates extends beyond bank profits. Increased borrowing costs may constrain demand for loans and mortgages, affecting household budgets and corporate investment decisions. Banks, while benefiting on the revenue side, must navigate these challenges to maintain long-term customer relationships and market share.
Furthermore, the government’s plan to impose a higher bank tax reflects broader societal expectations for financial institutions to contribute to economic recovery and public welfare. This move may prompt banks to reassess their operational efficiencies and innovation efforts to sustain profitability in a changing fiscal environment.
What This Means Going Forward
The latest financial results from one of the UK’s flagship banks highlight the profound influence of macroeconomic policies on corporate performance. With interest rates set to remain elevated to combat inflation, banks are likely to continue experiencing strong profit streams in the near term. However, the introduction of a higher bank tax signals a recalibration of the sector’s financial landscape, potentially tempering these gains.
Investors and industry observers should prepare for a period of adjustment, as banks respond to new tax obligations and evolving market conditions. Meanwhile, policymakers will need to balance fostering a competitive banking sector with ensuring that the benefits of economic growth are equitably shared.
Ultimately, the intersection of rising interest rates and changing tax policies will shape the trajectory of the UK banking industry, influencing its capacity to drive economic activity and serve customers effectively in the years ahead.