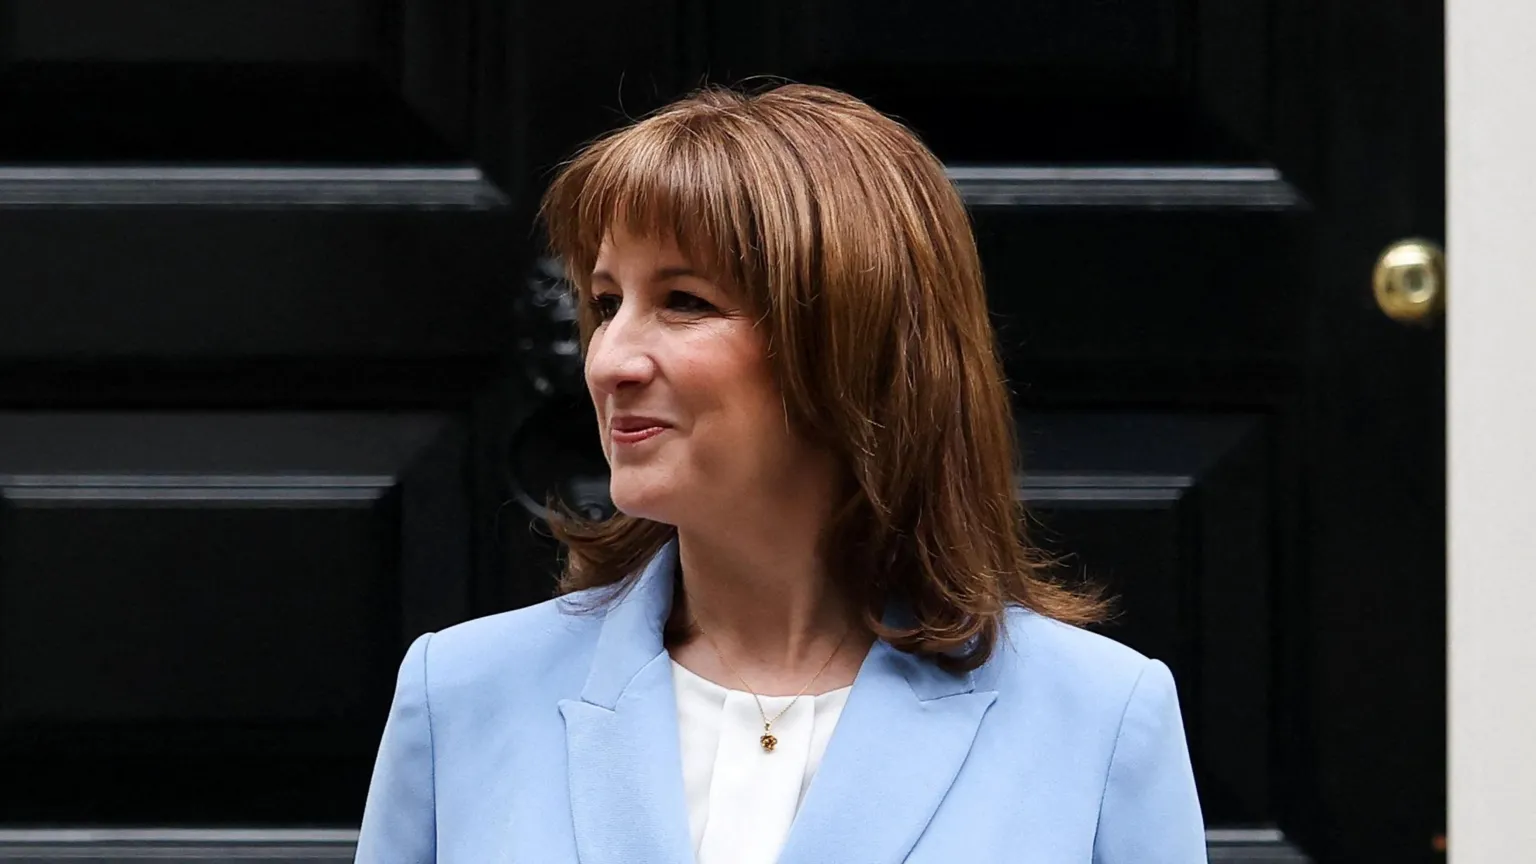
The UK’s economic forecast received a cautious update on 3 March 2026 as Chancellor Rachel Reeves delivered her Spring Statement. While the announcement avoided major tax hikes or spending shifts, it highlighted critical adjustments shaped by emerging global uncertainties and domestic challenges. Central to the update was the latest economic outlook from the Office for Budget Responsibility (OBR), which revised growth and employment projections against a backdrop of geopolitical tensions.
Economic Forecasts Adjusted Amid Global Uncertainty
The OBR downgraded its growth forecast for 2026, projecting the UK economy will expand by just 1.1%—a reduction from the 1.4% predicted in last November’s Budget. However, forecasts for 2027 and 2028 show a slight improvement, with growth expected to reach 1.6% in both years, marginally above previous estimates of 1.5%. This tempered outlook reflects the impact of the ongoing conflict in the Middle East, which Reeves acknowledged as a factor increasing economic volatility and uncertainty.
Unemployment is anticipated to rise modestly to 5.3% this year before gradually declining to 4.1% by 2030, indicating a cautious yet hopeful labor market trajectory. Inflation, which has been a persistent concern, is forecast to average 2.3% in 2026, edging down to the government’s 2% target by 2027. These figures suggest inflationary pressures are easing but remain a key consideration for policymakers.
Public Spending and Fiscal Headroom
Reeves confirmed that the OBR will postpone its full assessment of the government’s adherence to tax and spending rules until the next Budget, continuing a policy shift introduced last year. Despite this delay, the Chancellor reported an increase in the government’s fiscal “headroom” — the space available to borrow without exceeding day-to-day spending limits — rising from £21.7 billion to £23.6 billion. This provides some flexibility in managing the public finances amid economic uncertainties.
Similarly, the headroom related to the government’s rule to reduce debt as a share of national income has expanded to £27.1 billion. These figures reflect a cautiously improving fiscal position, suggesting the government is better placed than previously thought to manage borrowing and debt objectives without immediate drastic measures.
Housing Market and Immigration Trends
The housing sector faces mixed signals. The OBR predicts the average interest rate on existing mortgages will climb from 4.1% in 2026 to 4.5% by 2030, although these rates are lower than previously estimated. Housing construction, a vital factor in addressing the UK’s long-term supply shortage, is expected to decline from an average of 260,000 homes per year in the early 2020s to 220,000 in 2026/27. Encouragingly, housebuilding is projected to rebound to 305,000 annually by 2030/31, signaling a potential recovery in supply.
On immigration, net migration forecasts have been revised downward by 60,000 annually compared to November’s figures. This adjustment accounts for an increase in British nationals leaving the UK. Despite fluctuations, net migration is expected to range between 200,000 and 300,000 each year through the end of the decade, underscoring ongoing demographic shifts impacting labour markets and public services.
Policy Reversals and Fiscal Impact
The OBR highlighted two notable budget reversals that will affect government revenues. The expected income from taxing inherited farmland has been reduced by £100 million annually due to further softening of the policy announced last December. Additionally, the Treasury will absorb a £100 million yearly cost from January’s easing of business rates for pubs and music venues in England. These changes illustrate the government’s responsiveness to sector-specific pressures but also signal tighter future fiscal constraints.
Why This Matters
The Spring Statement 2026 reflects a prudent approach amid a landscape of global instability and economic headwinds. Chancellor Reeves’ cautious tone and the OBR’s downward revisions highlight the government’s awareness of emerging risks, particularly from international conflicts and domestic economic shifts. The modest fiscal headroom offers some breathing room, but the absence of significant new measures signals restraint, with a focus on stability rather than stimulus.
For businesses, homeowners, and workers, the revised outlook presents a mixed picture: slower growth and rising unemployment tempered by eventual improvements in inflation and housing supply. The adjustments in migration forecasts and policy reversals further complicate the economic environment, underscoring the challenges policymakers face in balancing growth, public finances, and social needs.
Looking ahead, the UK’s economic trajectory will depend heavily on how global uncertainties evolve and the government’s ability to navigate fiscal constraints while supporting key sectors. The Spring Statement sets a cautious baseline, but forthcoming Budgets will be critical in shaping the nation’s financial resilience and growth prospects in the coming years.